What should you do in the first hour of a home repair emergency?
In the first hour, protect people first, then stop the source of damage by shutting off water, power or gas as needed, and only then start photographing, calling professionals and thinking about costs.
Panic makes people skip steps, and skipped steps cost money. A homeowner who spends ten minutes searching for loan instant cash options while water is still running through a ceiling will face a bigger repair than one who finds the main shutoff first. Money matters, but it comes third. Safety and damage control come before any phone call to a lender, an insurer or even a contractor. A personal loan can wait an hour; a running supply line cannot.
Use this order whenever something goes wrong: get everyone, including pets, away from danger; stop the water, electricity or gas feeding the problem; move valuables and electronics out of harm's way; then document what happened. If you smell gas, see sparks, notice smoke or suspect structural damage, leave the house and call 911 or your gas utility's emergency line from outside.
- Know where your main water shutoff, electrical panel and gas meter valve are before you need them.
- Keep a flashlight, a basic wrench and towels where you can reach them in the dark.
- Save your plumber, electrician, HVAC company and insurance claim numbers in your phone today.
What should you do after a water leak or burst pipe?
After a water leak or burst pipe, shut off the water at the fixture or main valve, cut power to wet areas, remove standing water quickly and start drying within hours to limit mold and structural damage.
Most homes have a main shutoff where the water line enters the house, often in a basement, crawl space, garage or near the water heater. Turn it clockwise until it stops. If the leak is from a single fixture such as a toilet supply line or the hose behind a washing machine, the small valve behind that fixture may be enough. Then open a faucet on the lowest floor to drain pressure from the pipes.
Water and electricity are a dangerous mix. If water is near outlets, a power strip or the electrical panel, switch off the breakers for that area only if you can reach the panel while standing on a dry surface. Otherwise, call an electrician or your utility. Once the area is safe, mop, use a wet vacuum, pull up soaked rugs and run fans or a dehumidifier.
Timing matters because drywall, insulation and subflooring can start growing mold within a day or two in warm conditions. Professional water mitigation companies can bring industrial dryers and moisture meters. Their work often costs several hundred to a few thousand dollars (rough estimate), and insurers commonly expect you to take reasonable steps like this to prevent further damage. Keep the invoice, because it may be reimbursable and it tells you how much, if anything, you may need to cover with savings or a personal loan.
What should you do when the furnace or air conditioner fails?
When a furnace or air conditioner fails, check the thermostat, breaker and filter first, keep vulnerable people safe from extreme temperatures, and call a licensed HVAC technician if simple checks do not restore it.
Many no-heat or no-cool calls end up being something simple. Make sure the thermostat is set to heat or cool, the batteries are fresh and the setpoint is above or below the room temperature. Check for a tripped breaker labeled furnace, air handler or condenser, and look at the furnace switch, which often looks like a light switch on or near the unit. A badly clogged filter can also trip safety limits and shut the system down.
If those checks fail, protect the people in the house. In winter, an older relative or a baby may need to stay with family or use a safe electric space heater placed away from curtains and furniture. Never use an oven, grill or generator indoors for heat, because carbon monoxide can build up quickly. In summer heat, move to the coolest room, close blinds and use fans, or spend the hottest hours somewhere air-conditioned.
HVAC repairs vary widely. A capacitor, igniter or flame sensor replacement may run a few hundred dollars, while a failed blower motor or compressor can cost far more (rough estimates). Ask the technician whether the part is under the manufacturer's warranty, since many systems carry parts coverage for years even when labor is not included. Warranty coverage can shrink the bill enough that a personal loan becomes unnecessary or much smaller.
What should you do after an electrical failure at home?
After an electrical failure, check whether the outage is neighborhood-wide, reset a tripped breaker only once, and call a licensed electrician right away if you see scorch marks, smell burning or a breaker keeps tripping.
Start by looking outside. If neighbors are also dark, report the outage to your utility and wait. If only your home or part of it is out, open the panel and look for a breaker sitting in the middle or off position. Push it fully off, then back on. A breaker that trips again immediately is protecting you from a short circuit or overload, so leave it off and unplug devices on that circuit.
Some signs need urgent professional help: a warm or buzzing panel, a burning plastic smell, flickering lights across the whole house, outlets that are discolored or hot, or a partial outage where some lights are dim and others bright. That last symptom can point to a problem with the neutral connection, which can damage electronics and appliances. Shut off the main breaker if it is safe to reach and call an electrician or your utility.
Protect perishable food by keeping the refrigerator and freezer closed. Check on medical devices that need power and charge phones from a car if necessary. Small electrical repairs such as replacing a failed breaker or outlet may be modest, while a damaged service panel can cost much more, so get the diagnosis in writing. A written diagnosis also helps if you later compare personal loan offers, because you can request the exact amount instead of guessing.
How should you document home damage for repairs and insurance?
Document home damage with time-stamped photos and video before cleanup, a written list of damaged items, saved receipts for emergency supplies, and notes of every call with insurers and contractors, including names and dates.
Walk through each affected room slowly with your phone camera. Capture wide shots that show the whole space, then close-ups of the source of the problem, water lines on walls, damaged flooring, wet furniture and serial numbers on ruined appliances. A short video with you describing what you see can be even more useful later, when details blur.
Keep damaged items until your insurer says you can discard them, unless they are a health hazard. If wet carpet or drywall has to go right away, photograph it first and cut a small sample to keep. Save receipts for everything you buy or rent to limit damage: fans, tarps, buckets, a wet vacuum, a hotel room if the home is unlivable. Some lenders also ask what a personal loan will be used for, and a clear record of the damage makes that answer simple.
Start a single note on your phone titled with the date of the damage. Log every call, the person you spoke with, what they promised and any claim or job number. That one note can save hours of frustration when a claim or contractor dispute drags on.
How do homeowners insurance claims work for sudden damage?
Homeowners insurance generally covers sudden, accidental damage such as a burst pipe, minus your deductible, but usually excludes gradual wear, long-term leaks and lack of maintenance, so the cause of the failure matters.
Read your policy's declarations page and the section on water damage before you call. Most standard policies treat a pipe that suddenly bursts differently from a slow drip that rotted a cabinet over months. Flooding from outside water, such as a river or storm surge, typically requires separate flood coverage. Equipment breakdown, such as a furnace motor that simply wore out, is often not covered at all unless you have an endorsement or a separate home warranty plan.
Compare the likely repair cost with your deductible. If you carry a $1,000 deductible and the repair is $1,300 (estimates for illustration), filing a claim may not be worth it, since claims history can affect future premiums with some insurers. If the damage is larger or the cause is clearly sudden, report it promptly; many policies require timely notice.
- Call the claims line or file online, and write down the claim number.
- Ask what emergency mitigation the insurer expects and whether it has preferred vendors.
- Meet the adjuster with your photos, damage list and receipts ready.
- Get the adjuster's estimate in writing and compare it with contractor quotes.
- Ask how payment works, since checks may be issued in stages or jointly to you and a lender on the home.
Even an approved claim leaves a gap: the deductible, items the policy excludes and the wait for payment. That gap is where many households end up comparing a credit card, savings and a personal loan.
How do you get fair repair quotes during an emergency?
Fair emergency repair quotes come from licensed, insured contractors who inspect the damage and give a written, itemized estimate, ideally compared against at least one other bid once the immediate danger is under control.
Separate the emergency fix from the full repair, especially if a personal loan may cover part of the cost. A plumber may need to cap a burst line tonight, and that visit is worth paying for right away. The permanent repair, such as replacing a section of pipe, new drywall and fresh paint, can usually wait a day or two for a second opinion. Asking for that split keeps you from signing a large contract while stressed.
Verify the contractor's license with your state or local board, ask for proof of insurance, and read recent reviews. Be wary of anyone who knocks on your door after a storm, pressures you to sign immediately, asks you to sign over your insurance payment, or wants most of the money upfront. A reasonable deposit for materials can be normal, but the bulk of the payment should follow completed work.
For water heater failures specifically, our breakdown of rough water heater replacement costs for tank and tankless units shows what parts, labor and permits typically add up to, so you can tell whether a quote is in a reasonable range.
How can a loan instant cash request help pay for urgent repairs?
A loan instant cash request can connect homeowners with independent lenders that may offer personal loans from $500 to $5,000, which can cover a deductible, an excluded repair or a bill due before insurance pays.
Start with the cheapest money available. An emergency fund, a contractor's interest-free payment plan, or an insurance advance for living expenses may cover part of the bill. Credit cards are fast but expensive if the balance stays for months, which is why some homeowners compare them with personal loans for larger bills. Some credit unions offer small emergency loans to members at lower rates, and a nonprofit credit counselor can help if the repair arrives on top of existing debt.
A fixed-rate personal loan sits between those options. You know the payment, the term and the total cost from the start. Our service is free and is not a lender: one form is shared with a network of third-party lenders, and a lender that can work with your request may present an offer with its own rate and terms. You are never obligated to accept, and terms commonly run about 3 to 36 months depending on the lender and state. To see the process step by step, read how our loan request process works.
For a sense of cost, a $1,000 loan for an emergency repair repaid over 12 months at 26.48% APR comes to about $95.76 per month and $1,149.17 in total, assuming no origination fee (estimate only). Over 6 months at the same estimated rate, the payment is about $179.77 and the total about $1,078.64. Shorter terms raise the payment but lower total interest, so choose the shortest personal loan term whose payment still fits your budget.
Many lenders prequalify with a soft inquiry and run a hard inquiry only when you accept, and funding often arrives by ACH as soon as the next business day after approval and e-signature, though timing depends on the lender. Quick cash loans that promise unrealistic speed or ask for fees before funding deserve suspicion. If you need money faster than a lender can send it, our guide to options when you need money in a hurry covers other short-term steps.
What does a 48-hour home emergency timeline look like?
A practical 48-hour timeline moves from safety and shutoffs in the first hour, to documentation and emergency service the same day, to insurance, quotes and payment decisions on the second day.
| Time window | Main goal | Key actions |
|---|---|---|
| 0–1 hour | Safety and shutoff | Move people and pets, shut off water, power or gas, call 911 or the utility if there is danger |
| 1–4 hours | Limit damage | Remove water, move belongings, open windows or run fans, call an emergency plumber, electrician or HVAC tech |
| 4–12 hours | Document | Photos and video, damage list, receipts, start a call log |
| 12–24 hours | Notify and stabilize | Report the claim if it makes sense, confirm temporary repairs, arrange a place to stay if needed |
| 24–48 hours | Plan the full repair | Meet the adjuster, collect written quotes, compare payment options, set a budget |
Not every emergency fits neatly into those windows. A failed furnace in a cold snap may compress everything into a single evening, while a small slow leak may give you days to plan. The order still holds: safety, damage control, documentation, then money.
By the end of day two, you should know the total repair cost, how much insurance may cover, and how much you need to fund yourself. That final number, not a rough guess, is what you should compare against savings, a contractor plan or personal loan offers.
How do you decide whether to borrow for a home repair?
Borrowing for a home repair makes sense when the repair cannot wait, savings fall short, and the monthly payment fits your budget without crowding out rent, utilities, groceries or existing debt payments.
Ask three questions. First, is this repair urgent, or can a temporary fix hold until you save? A tarp on a roof or a capped pipe can buy weeks. Second, what is the cheapest money you can access, and does it cover the full need? Third, if you borrow, can you comfortably make the payment for the whole term, even in a month with an unexpected bill? Personal loans work best when all three answers point the same way.
When comparing loan instant cash offers or any other financing, look at the APR, any origination fee, the term and the total repayment amount, not just the monthly figure. A longer term may feel easier now but costs more over time. Borrow only what the written quote requires, and resist rounding up for a cushion you may not need. Fast cash loans online can be useful in a true emergency, but a personal loan taken for more than the repair needs adds interest without solving anything extra.
Our guide to personal loans for urgent home repairs like plumbing, HVAC and electrical work explains typical uses, amounts and requirements in more detail. A repair loan should end when the repair is finished and paid off, not linger long after the problem is forgotten.
How can you prepare for the next home emergency?
Preparing for the next home emergency means labeling shutoffs, building a simple emergency kit, scheduling basic maintenance and setting aside a dedicated repair fund, even a small one, that grows every month.
Spend one afternoon learning your house. Tag the main water valve, the gas shutoff and the electrical panel with bright labels, and make sure every adult in the home knows how to use them. Check that the panel directory actually matches the rooms; many are years out of date. Keep a wrench near the gas meter if your utility recommends it.
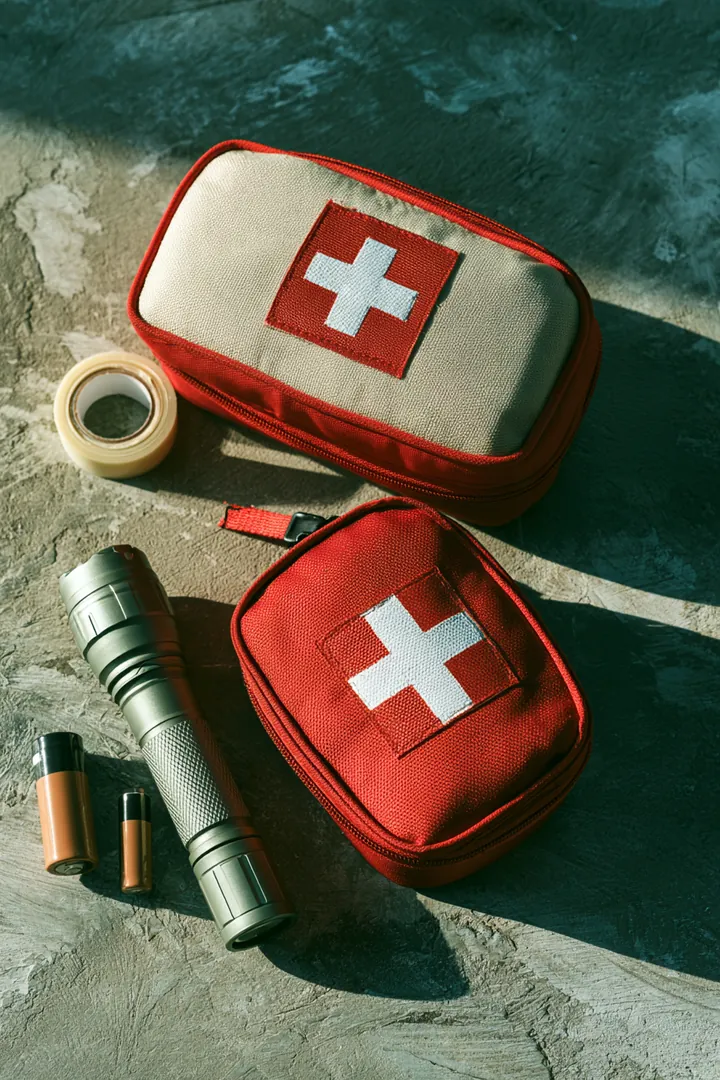
Build a kit and store it where you can reach it during a power outage: a first aid kit, flashlights, spare batteries, duct tape, a utility knife, work gloves, a few heavy-duty trash bags and towels. Add a water leak alarm or two near the water heater, washing machine and under sinks; they are inexpensive and can catch a leak early. Change HVAC filters on schedule and book a yearly tune-up for heating and cooling equipment.
Finally, start a home repair savings account. Many homeowners aim for a set amount each month, adjusted to the age of the roof, water heater and HVAC system. Even a modest fund can cover a service call or deductible, which shrinks the amount you might ever need from a personal loan. Households that plan ahead are far less likely to be searching for loan instant cash at midnight with water on the floor. The goal is that the next emergency becomes an inconvenience rather than a financial crisis.
How Can You Get Emergency Cash Immediately?
Ranked, realistic ways to raise money for an urgent bill, with pros, cons and honest timing for each option.
What Does a Water Heater Replacement Cost?
Rough cost ranges for tank and tankless water heaters, including labor, permits, haul-away and common extras.